Buju Stanciu & Asociații Secures Landmark Tax-Litigation Victory Before Romania’s High Court

Buju Stanciu & Asociații has obtained a landmark ruling that strengthens fiscal certainty for energy-sector investors. On 24 June 2025, the Romanian High Court of Cassation and Justice annulled a supplementary corporate-tax assessment of EUR 1.2 million together with all accessories, levied against Energy Republic Trading.

The disputed assessment arose from an October 2022 audit in which the tax authority (ANAF) treated an uncollected RON 29.57 million “early-termination” receivable under an EFET power-trading contract as taxable income and rejected RON 4.6 million in joint-venture expenses as non-deductible. Litigators Marius Stanciu (Partner) and Vlad Mureșan (Senior Associate) demonstrated that both positions violated the Fiscal Code’s principles of certainty and predictability.

The High Court agreed, holding that litigious receivables cannot be taxed until they become certain and enforceable and confirming that legitimate business costs remain deductible even when related revenues are deferred. The judgment clarifies how account 473 (“Transactions Pending Clarification”) should be used and curbs the growing practice of “pre-taxing” hypothetical gains or re-characterising bona-fide expense, issues common across European energy markets.

See more articles from our member firm in Romania, Buju Stanaciu & Asociatii.

Exploring Opportunities: The Spanish Special Tax Regime for Impatriates

The Spanish Special Tax Regime for Impatriates could be an alternative to the legislative changes in Portugal and the UK.

The measures approved by the Portuguese and British governments represent a significant change in taxation for expatriates and international professionals. Can the Spanish tax regime be an alternative? It can be very attractive for people moving to Spain, especially in the case of individuals with a high level of income.

Read the full article here.

See more articles from our Spanish member firm Toda & Nel-lo.

Renewable energies sector in Spain: possibility of applying the exemption of Article 21 CIT Law in the transfer of SPVs shares

The construction and start-up of renewable energy production installations, whether solar photovoltaic plants or wind farms, requires many procedures.

The Directorate General of Taxation (DGT) has recognized the possibility of applying the exemption of article 21 of the Corporate Income Tax Law (CIT Law) (95% exemption, in general) to capital gains derived from the transfer of shares in subsidiaries dedicated to the development of photovoltaic solar plants.

Read the full article here.

See more articles from our Spanish member firm Toda & Nel-lo.

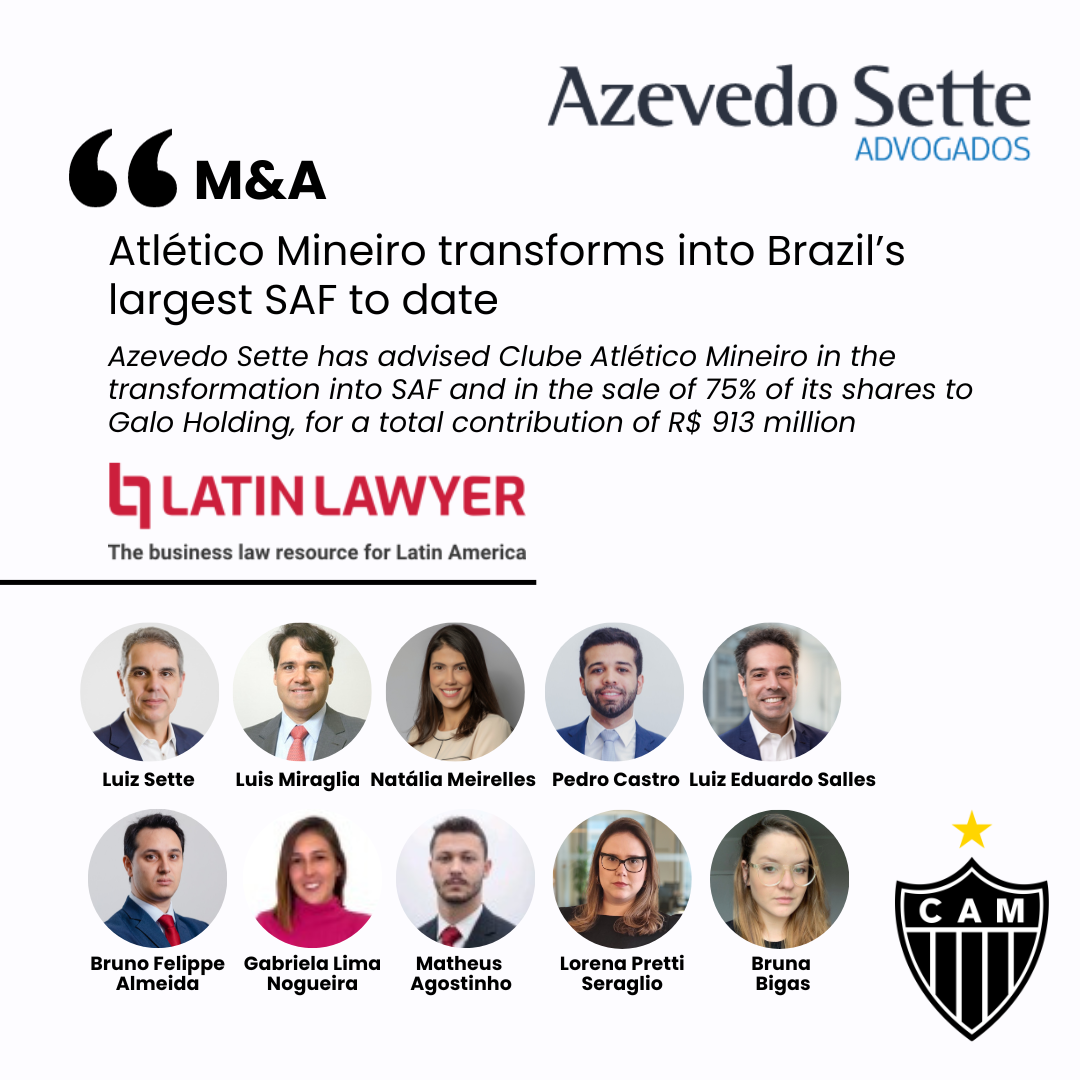
Azevedo Sette has advised Clube Atletico Mineiro in the transformation into SAF

Azevedo Sette has advised Clube Atletico Mineiro in the transformation into SAF and in the sale of 75% of its shares to Galo Holding, Ricardo Guimaraes and FIP Galo and FIP Galo Rei for a total value of R$ 913 million. They have been working with the club, the board and the officers of Atletico for more than year in the preparation of the team to get all Board approvals, transfer the assets into a Sociedade Anonima de Futebol and assisted Atletico in the process of restructuring, M&A and filing within CADE. They have also assisted Atletico in the restructuring of Arena MRV, the transfer of Arena MRV and the Training Facilities into the SAF.

This is the largest and most complex transaction already executed in soccer in Brazil, with one of the most prominent teams in the country, a complex debt structure, in addition to a brand new stadium and a combination of investors.

Azevedo Sette’s partners Luiz Sette and Luis Miraglia led the series of transactions that culminated in the signing on September 1st with the help of Tax Partner Bruno Felippe Almeida, antitrust Partner Luiz Salles, Senior Associates Natalia Meirelles Barros and Pedro Henrique De Castro Oliveira and contribution of Lorena Pretti Seraglio, Bruna Bigas, Gabriela Lima Nogueira and Matheus Araujo Aiala Agostinho.

Read the full article here.

BOYANOV & Co. Advised Ceska Sporitelna on Refinancing of Aricoma Group’s Loan for Musala Soft AD Acquisition

BOYANOV & Co. advised Česká spořitelna and a syndicate of banks on the refinancing of Aricoma Group’s loan from 2022, which supported the acquisition of Musala Soft.

The ARICOMA Group, a top IT service provider in Central Europe, has a strong presence in Scandinavia and serves over 1,000 clients in 18 markets.

Their team was led by partner Damian Simeonov and also included principal associate Ralitsa Nedkova and associate Dimitar Mihaylov.

Read the full article here.

Tax obligations for foreign business activities in Cameroon

As early as the 70s, Cameroon negotiated and signed several important texts aimed mainly at avoiding double taxation of income from foreign business activities in Cameroon and preventing tax evasion or establishing mutual assistance rules in tax-related matters.

As of December 31st, 2022, there are ten tax treaties in force in Cameroon. These include bilateral treaties between Cameroon and countries such as the French Republic; Canada; Tunisia; the Swiss Confederation; the Republic of South Africa; the Federal Republic of Germany; and the Kingdom of Morocco and multilateral conventions such as the double taxation convention on income between CEMAC member states; the convention on mutual administrative assistance in tax matters drawn up in 1988 and amended in 2010; and the Multilateral Convention to implement tax treaty-related measures to prevent base erosion and profit shifting.

Other than the above treaties, foreigners (natural persons or companies) without a head office in Cameroon but carrying out business activities therein are subject to registration and tax declaration formalities.

Registration and tax declaration of foreign business activities in Cameroon

In Cameroon, save the existence of a treaty for the avoidance of double taxation of income, foreigners without a head office in Cameroon but carrying out business activities therein must be registered with the tax administration and make the required tax declarations.

For the registration and tax declaration formalities, the foreigner must appoint a solvent representative accredited by the tax authorities. Upon this registration, a Tax Identification Number (TIN) shall be granted to the foreigner to make the required tax declarations.

In consideration of the income derived from their activities in Cameroon, these foreigners are required to spontaneously declare and make an advance payment representing either 2%, 5%, 10%, 14%, or 20% of their turnover generated during the previous month no later than the 15th of each month, depending either on their tax system or the nature of their activities. This advance payment is increased by 10% for the additional communal centimes.

Furthermore, these foreigners shall file an annual declaration of the results obtained from their operations during the previous year no later than the 15th of March of each year.

From the above, respecting the registration and tax declaration formalities shall enable foreigners without a head office in Cameroon to securely carry out business activities.

The specific case of foreign operators of electronic commerce (e-commerce) platforms in Cameroon

Operators of e-commerce platforms with no head office in Cameroon must apply to be registered with the Cameroonian tax authorities, failure of which, access to the said platform shall be suspended on the Cameroonian territory.

The formalities for registration, declaration, and payment of taxes collected by the e-commerce platforms can be done online through the Internet portal of the tax administration.


For more information on this topic please contact our member 4M Legal and Tax

Foreign tax credit under American new legislation and Brazil’s convergence towards OECD guidelines

On December 28, 2021, the American Treasury Department released final regulations (TD 9959, Final Regulations) regarding foreign tax credit (FTC) to be offset in the USA. In a nutshell, according to the referred legislation, in order to be offset, the tax paid abroad must be reasonably similar to US tax rules.

Brazilian tax legislation does not hold the principles that would allow Brazilian FTC in the US under TD 9959. Brazil levies withholding taxes (WHT) at the payment source, unlike the production source required by the new US legislation. Additionally, Brazilian transfer pricing (TP) rules are not currently under Organisation for Economic Co-operation and Development (OECD) guidelines, i.e., the arm’s length principle (ALP) is not strictly observed.

In this sense, if there is a WHT burden on a remittance from Brazil to the US, the WHT offset would not be allowed for the American taxpayer. Also, considering the scenario of a Brazilian company as a subsidiary of an American entity, there would be no FTC regarding Global Intangible Low-Taxed Income (GILTI) legislation – American Controlled Foreign Companies (CFC) rules.

Nevertheless, Brazil has initiated its accession process for OECD membership. A Roadmap was published by the Organization on June 10, 2022, which says that OECD Committees will evaluate Brazilian legislation and propose alterations to enable Brazil’s accession. The Federal Decree #11.105 was published in Brazil on June 27, 2022, determining the domestic groups that will develop the analysis along with OECD Committees.

Brazilian Federal Revenue (RFB) already initiated the studies about the legislative changes that are needed regarding TP: a new approach under OECD guidelines was presented by the RFB, which affirmed that the respective bill will be available soon in order to start the legislative process. A seminar hosted by RFB and IDB (Inter-American Development Bank) occurred on June 29, 2022, demonstrating the updates on the convergence towards OECD standards. The private sector was invited to present its inputs and multiple countries’ representatives shared their experience with OECD guidelines so that Brazilian tax authorities could be prepared regarding its system.

In addition, international commerce organizations have been discussing the TD 9959 with the Brazilian Economy Ministry, pointing out that there will be a double taxation between Brazil and the US. At a recent meeting, it was proposed that Brazil should request US Treasury an extension of two (2) years for starting the application of the new rules, so that Brazil would have time to accommodate US requirements on its legislation. The new approach for TP and the negotiation of a Double Tax Treaty (DTT) were also discussed, focusing on having the TP bill as soon as possible and then initiating the DTT discussions.

At the seminar which took place on June 29, however, the USA representative said that the Final Regulations will need to be applied by the end of 2022 and that the observance of the ALP in Brazil is a condition to start the discussions for the DTT.

We emphasize, though, that there is no need to have a DTT in order to have FTC in the USA: if the TD 9959 requirements are met, the credit is allowed. Additionally, before the Final Regulations, it was possible to offset Brazilian FTC in the US.

Taxpayers should, therefore,  observe the next steps in Brazil’s convergence towards OECD guidelines, especially regarding the possibility of American entities offsetting Brazilian FTC.

New Tax Group Established

We are pleased to inform you that a Tax Practice Group has been established within the LNI.

The Group members will meet online twice a year to share industry news, opportunities and expertise. Additional meetings may be scheduled on an ad-hoc-basis.

We will be exchanging information on the latest case law, and discussing how we can work together to promote our services to reach a wider audience.

To join the LNI Tax Group, please contact the group Chairperson Nina Kuntschik at Nina.Kuntschik@snp-online.de